All articles
What Derails A CHOICE (ICHRA) Rollout Is Rarely The Law
Chris Vanderwolk, Director of Compliance and Innovation at OneDigital, on what the compliance work for a CHOICE (ICHRA) arrangement actually involves, and why rollouts slip on practical decisions nobody owns rather than on the rules.
Make Benefits Brief News one of your go-to sources on Google

Every day you spend deliberating is a day your window closes on optionality.
Chris Vanderwolk
Ask a broker what worries them about a first CHOICE rollout and the answer usually starts with compliance: the notices, the classes, the plan documents. Chris Vanderwolk spends his working days on those rules, and his view is that they are the knowable part.
The compliance list for CHOICE, previously known as ICHRA, is shorter than a group plan’s in some places and the same in others. What derails a rollout is usually something else: a decision that takes too long, a coverage question nobody raised early, a project nobody owns.
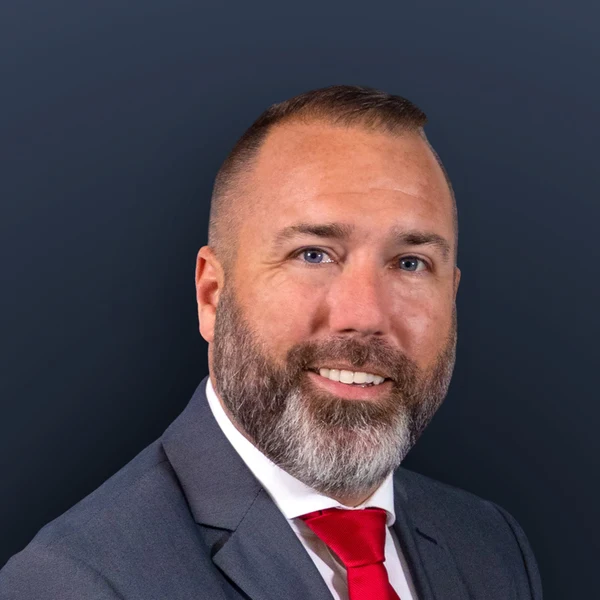
Chris Vanderwolk is Director of Compliance and Innovation at OneDigital, covering Greater Pennsylvania, New Jersey and Delaware, with 19 years in the industry. An ERISA attorney, he chairs the Legislative Council of NABIP, the National Association of Benefits and Insurance Professionals, this year. He spoke to Benefits Brief News for himself, not for OneDigital.
Start with what goes away, and what stays
“The compliance rules are simplified in many regards compared to a group plan,” Vanderwolk says, “but there’s still specific nuances that have to be done.”
An employer offering CHOICE is not sponsoring the major medical plan, so the obligations attached to that plan move to the carrier. Prescription drug data collection reporting and gag clause attestations “get to be somebody else’s problem,” and so does transparency in coverage. SureCo’s 2026 State of ICHRA report lists the same change: certain attestations, such as gag clause reporting, are no longer required for individual-market coverage.
What stays is familiar from any group plan. “They’re still sponsoring an ERISA plan”: a plan document, a summary plan description, and an arrangement that does not discriminate in eligibility or benefits. In his example, executives cannot get $1,000 a month while everyone else gets $200. Allowances can differ only as the CHOICE rules allow, by class and by age, up to three times the youngest employee’s amount.
Classes are where early advice went wrong. Some employers were told “you could do this for just your sick people to get them off the plan.” His answer: “that’s not a class.” Classes are defined, such as full-time, part-time, seasonal or rating area, and “the administrators knew and internalized the rules faster than maybe everybody in the market had.”
The one part that grows is the contribution math: dozens of age-based rates across rating areas, instead of the four or five tiers of a larger group plan. That is why he calls running CHOICE without an administrator “possible, but not really advisable.” The challenges today, in his view, are “more practical than they are on the compliance side.”
Name the trade-offs before enrollment
Individual coverage is based on where the employee lives. In New Jersey, where Vanderwolk lives, many people commute into New York or Philadelphia every day, and “if you spend all your days in a different state and come back at night, the doctor’s office might be closed.” Salespeople who travel across states, and employees in states such as Wyoming or Alaska where “the market’s pretty thin,” raise the same question.
So can the person making the decision. An executive who spends the winter in Florida, with no spouse’s plan to fall back on, can “stop the whole program in its tracks” with one question: “What do you mean I can’t go to the doctor for four months when I’m in Boca Raton?”
None of this is new. Checking whether a network covers where people live and work is part of every group renewal. Under CHOICE the check happens person by person, and the failures he sees come from “not aggressively owning the process”: selling the model as a cure-all instead of explaining it “warts and all.” The employer gets predictability, stability and less compliance work. Some of its people get a different experience. Both halves belong in the first meeting.
“We’re not just buying a cheaper version of what we’ve always had.”
Chris Vanderwolk, Director of Compliance and Innovation, OneDigital
Decide early, because employees need the time
The deadline he worries about belongs to the employees. “Most of the delays that I’ve seen end up coming down to just indecisiveness or fear, uncertainty, and doubt.” Every week spent deciding is a week employees lose to work out which drugs, doctors and hospitals matter to them. “Those become very individualized conversations, and that takes time to figure out.”
“You didn’t succeed because you got the paperwork in. You just deferred your problems into January and February when people are unhappy.”
Chris Vanderwolk, Director of Compliance and Innovation, OneDigital
Some friction comes with any change of this size. Preparation removes most of it, which is why the communication work sits before the enrollment window, not inside it.
Put the project plan in writing
Asked what a broker should have in writing before a first client goes live, Vanderwolk names a project plan, not a legal document: milestones and owners agreed with the administrator as soon as the client says yes, so everyone can be held to them. “This is really just a project management exercise and nobody’s going to own it” unless the broker steps up. HR teams that have run a CHOICE enrollment describe the same need for a single point of contact.
Why local advice is in court
Local knowledge is also why his work at NABIP has reached a courtroom. NABIP has sued the Department of Health and Human Services in federal court in Maryland over a CMS moratorium that barred agents and brokers who were not registered with the federal Marketplace for Plan Year 2026 from registering to sell 2027 plans on HealthCare.gov. CMS said the freeze would prevent fraud and estimated that nearly 19,000 agents and brokers would be blocked, according to Healthcare Dive. Vanderwolk backs going after the fraud but calls the freeze “overbroad”: many CHOICE platforms refer employees back to local agents, and “healthcare is local.” On November 5, the federal court in Maryland lifted the moratorium, according to NABIP.
He expects the model to keep growing, with employers staying in CHOICE even when they change platforms, which tells him “the model works and they like it, but they’re looking for some more enhancements.” It is “not a perfect solution, but it has some real advantages.” The rules are written down. What decides a rollout is whether someone makes the decision in time, puts the hard questions on the table, and owns the plan from yes to go-live.
Sources:
- SureCo, 2026 State of ICHRA Report
- Healthcare Dive, report on NABIP’s lawsuit over the HealthCare.gov agent and broker registration freeze (October 16, 2026)
- NABIP, press release on the court ruling (November 5, 2026)